为落实《关于规范金融机构资产管理业务的指导意见》中关于净值化管理的要求,促进基金行业健康发展,中国证券投资基金业协会(以下简称协会)在2017 年发布的《中国基金估值标准》基础上,加入《私募投资基金非上市股权投资估值指引》、《私募投资基金非上市股权投资估值范例汇编》和《固定收益品种SPPI 测试方法示例》等内容,编纂形成《中国基金估值标准2018(China Fund Valuation Guidebook 2018)》。
其中,《私募投资基金非上市股权投资估值指引》是协会在3 月30 日发布的自律规则,标志着对公允价值的探索已经延伸至非上市股权领域。为便于理解,协会在标准中附上了中国基金估值标准体系金字塔图示以及涵盖企业初创期、成长期、成熟期、发行未上市、已上市、定增、老股转让、大宗交易、停牌和退市等全生命周期的股权估值参考图等。《私募投资基金非上市股权投资估值范例汇编》和《固定收益品种SPPI 测试方法示例》是为股权和债权估值中可能遇到的难点问题提供参考。估值能力是资产管理行业的核心竞争力,资产管理机构应持续关注投资标的的估值变化,将估值工作贯穿于募投管退环节,努力提升标的估值,为投资者发现价值、创造价值。提升专业买方机构定价能力有助于促进资本市场博弈有效性。协会估值小组未来将顺应行业发展需求,不断完善中国基金估值标准体系,打造中国基金投资业绩标准(China Investment Performance Standards)。
现发布《中国基金估值标准2018》(China Fund Valuation Guidebook 2018)并将其公布于协会官方网站的基金估值栏目,详见网址<a href="http://www.amac.org.cn/cms/browsepriv/catalog?ID=11313,">http://www.amac.org.cn/cms/browsepriv/catalog?ID=11313,</a> 供广大基金从业人员学习参考。
中国证券投资基金业协会
二零一八年十二月十一日
中国基金估值标准2018
China Fund Valuation Guidebook 2018
中国证券投资基金业协会
托管与运营专业委员会估值工作小组编
中国证券投资基金业协会
Asset Management Association of China
中国基金估值标准
China Fund Valuation Guidebook 2018
编写组
Compilers主编:洪磊Editor-in-Chief:Hong Lei副主编:钟蓉萨Associate Editor:Zhong Rongsa基金业协会成员:熊歆汤明珥陈硕夫赵前聚
陈偲路玺Members of AMAC: Xiong Xin Tang Yueyue Chen Shuofu
Zhao Qianju Chen Si Lu Xi普华永道中天会计师事务所成员:薛竞朱宏宇Members of PwC: Xue Jing Zhu Hongyu中国工商银行成员:胡捷朱正Members of ICBC: Hu Jie Zhu Zheng非上市股权投资估值范例汇编参与成员:歌斐资产管理有限公司苏州元禾控股股份有限公司Participants of Case Study on Valuation of Unlisted Equity Investments of Private Equity Funds:Gopher Asset Management Suzhou Oriza Holdings Corporation固定收益品种SPPI 测试方法示例参与成员:中债金融估值中心有限公司Participants of Case Study on SPPI Testing of Fixed Income Instruments:ChinaBond Pricing Center CO. LTD.To learn more about China Fund Valuation5please contact:如需获得关于中国基金估值的更多信息,敬清联系:
Tel.电话:+86.10.66578410
Email 电邮:guzhi@amac.org.cn开本/140 毫米X210 毫米1/32 印张/9.75 字数:105 千版本/2018 年9 月第2 版印次/2018 年9 月第1 次印刷
前言
PREFACE
基金业协会估值小组的公允价值探索之路
2018 年4 月270,《关于规范金融机构资产管理业务的指导意见》(以下简称《资管新规》)正式发布。其中,针对资产管理行业存在的“资金池”、“刚性兑付”等问题,《资管新规》强调了资管产品应当实行净值化管理和公允价值计量。
净值化管理,很容易被解读成为字面的含义:产品份额化,以份额净值报价。然而,以破除刚兑为目的的净值化管理真正的核心,强调的是对投资标的进行公允价值计量。破除刚兑,要求产品在计算投资人的权益时,能够及时体现出投资运作的成果,暴露出当前承担的风险。只有在以公允价值计量的前提下,上述目的才能得以实现。
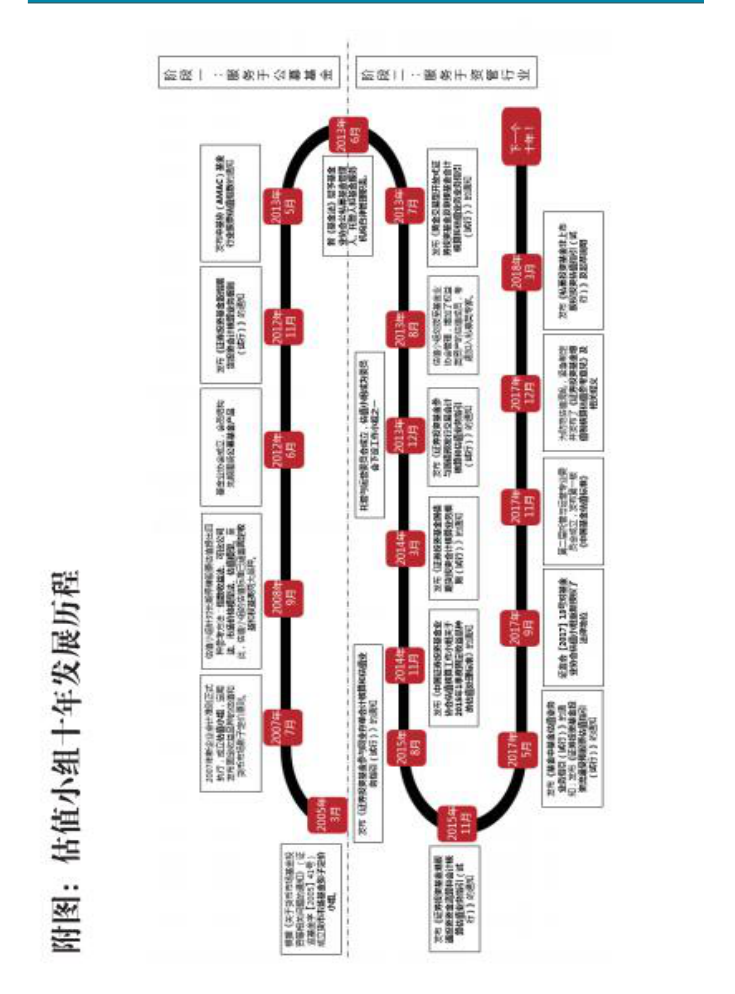
对公允价值计量的理解,并非是一蹴而就的。基金行业成立的20 年来,走的是一条在不断完善制度建设中可持续发展的道路。中国证券投资基金业协会(以下简称“协会”)依据《证券投资基金法》授权,立足行业自律,围绕协会7+2 自律规则体系,发布了《私募基金服务业务管理办法》,明确了基金服务机构的业务边界和履责要求。此外,根据《中国证券监督管理委员会关于证券投资基金估值业务的指导意见》,为提高估值的合理性和可靠性,协会可建立基金估值工作机制。协会在托管与运营委员会(以下简称“委员会”)下设立基金估值小组,逐步构建了行业估值标准体系。2005 年影子价格小组的成立,引入了中央国债登记结算有限责任公司(以下简称“中债”)作为首家基金估值基准机构,标志着资产管理行业从市值法到公允价值的探索。自此,货币基金使用中债提供的估值价格作为影子价格对“偏离度"指标进行控制o 在此之前,货币市场基金使用的估值方法与目前的银行理财产品具有一定的相似性,即通过摊余成本法调整当期收益,从而达到控制收益率水平的目的。2008 年发布的《关于停牌股票估值的参考方法》,打破了停牌股票釆用市价估值的传统方法,推荐釆用更为公允的估值方法,帮助基金行业有效地应对金融风险。2014 年11 月发布的《固定收益品种的估值处理标准》,引入中证指数有限公司作为第二家基金估值基准机构,形成多家估值基准机构服务基金行业的格局。2017 年9 月发布的《流通受限股票估值指引》,进一步明确流通受限股票的范围,首次引入看跌期权模型,重点解决定增基金的公允价值估值问题。2017 年底的营改增90 号文,第一次认可了协会引入的估值基准机构,说明未来公允价格应当成为税收语言嫁接于资产管理行业的纽带。2018 年3 月发布的《非上市股权估值指引》,标志着对公允价值的探索已经延伸至非上市股权领域,大大提高了股权基金的价值发现能力。
2018 年,既是公募基金成立20 年周年,也是大资管行业的元年。《资管新规》强调了资管行业的根本目的是“服务实体经济”,资管行业既需规范,也要发展。估值能力是资产管理行业的核心竞争力,资产管理机构应持续关注投资标的估值变化,将估值工作贯穿于募投徳时,努力提升标的估值,为投资者发现价值、创造价值。提升专业买秫构定价能力有助于促进资本市场酬有效性。估值小组未来将继续顺应行业发展的需求,不断完善中国基金估值标准体系。一、持续覆盖各类投资标的
当前,估值小组建立的估值指引体系,已涵盖固定收益类、权益类和衍生金融产品,包含“股票、港股通、流通受限、国债预发行、固定收益品种、同业存单、股指期货、国债期货、基金中的基金、黄金ETF 和联接基金、非上市股权”等六大类十一项投资标的。下一步,协会将根据行业发展需求,致力于覆盖全品类投资标的估值。估值标准体系目前已经被广泛应用在公募基金、证券公司资产管理计划、基金专户、期货资管等,并且被推广至企业年金、职业年金、保险资管、银行理财、信托计划等资产管理行业,同时也适用于自营投资业务。估值小组将继续探索并引领公允价值计量工具的使用,引领资管产品净值化管理。
二、规范业绩报酬计提规则基金的本质是受托理财,私募基金管理人向合格投资者提供专业的受托理财服务,通常会收取两种费用,一种是以基金资产净值作为计算基数的管理费,另一种是以基金收益表现或投资者资产增值额作为计算基数的业绩报酬。私募基金收取业绩报酬的目的是使管理人与投资者利益趋于一致,合理的业绩报酬机制有助于激励管理人承担适当风险,为投资者创造更高的收益,最终实现管理人与投资者双赢,达到“收益共享”的目的。
私募基金行业尚未形成统一的业绩报酬提取规则,实践中存在业绩报酬收取方式繁复多样、信息披露内容不统一等问题。估值小组正在并将持续引导私募基金建立规范、合理的业绩报酬相关机制,规范业务操作,明确信息披露内容,公平对待投资者,保护投资者利益。
三、加强资管行业税收相关政策研究
税收作为国家治理体系的重要组成部分,具有筹集财政收入、调节分配、促进结构优化的职能作用,在服务新时代改革发展、促进社会公平方面应当发挥重要作用。在资管行业,促进行业公平发展的税制安排至关重要,中性税负、纳税机制清晰是基本要求。资管产品的相关税收应当有利于金融资本的循环,促进金融资本以高效的方式配置到实体经济中。估值小组作为连接基金语言与税收语言的纽带,持续开展税收政策研究,促进行业交流,为推动资管行业税制顶层设计奠定基础。
四、规范业绩比较基准在现代金融中,业绩比较基准已经成为影响市场的重要因素。对于基金而言,合适的业绩比较基准能够准确的反映基金的投资目标和投资策略,便于投资者根据自身的风险收益偏好选择合适的基金产品,相对准确地分析基金管理人的管理能力。对于基金管理人而言,业绩比较基准决定了投资范围和投资目标,如果管理费与业绩比较基准相挂钩,业绩比较基准将直接决定最终的管理费收入。对于资本市场而言,如果以某一指数为业绩比较基准的资产管理规模较大,那么该指数的变动将引发系统性的资金流变动,进而对相关资产产生系统性的影响。由于业绩比较基准对市场参与者以及市场本身,存在举足轻重的影响,加之基准使用者在实际应用中存在一定的偏失,因此国际市场对基准行业的监管日趋完善。当前,估值小组正在结合国际经验和中国市场现状,制订基金业绩比较基准指引,改善国内基金偏离基准的现象,进一步保护基金持有人利益。
随着中国资本市场对外开放的步伐加快,继沪港通、深港通、基金互认之后,中国资本市场又将迎来越来越多的全球参与者。规则就是话语权,标准就是稳定器,中国基金估值标准体系在基金行业国际合作与交流中建立对话平台,在资本市场双向开放中明确业务规则,必将为基金行业的“引进来”和“走出去”起到重要的桥梁和纽带作用。
结语
为便于广大从业人员学习和了解基金估值,提高专业化水平,基金业协会将历年发布的估值标准编纂成册,并对行业内较为成熟的非上市股权估值实践进行总结汇编,供大家学习参考。
中国证券投资基金业协会会长洪磊
二零一八年八月
Preface
AMAC’s Exploration on Fair Value Measurement
On April 27th of 2018, The Guiding Opinions on Regulating Asset Management Business of Financial Institutions (herein after referred
,? ) was officially to as the "New Regulations on Asset Management released. Among which, particularly concerning the problems including ucapital pool" and urigid repayment" in the asset management industry,the New Regulations on Asset Management emphasizes that asset management products should implement net value based management and fair value measurement.
Net value based management can be easily interpreted literally:product unitization, quoted as the unit net asset value. However, the real core of net value based management, with the purpose of breaking rigid repayment, is the fair value measurement of the investment target.Breaking rigid repayment requires the product to reflect the result of the investment operation in time and to expose the current undertaken risks when calculating the investors,rights and interests.The above goal can only be realized under the premise of fair value measurement.
The interpretation of the fair value measurement is not a one-step process. In the 20 years since the establishment of the fund industry,it has been walking through a road of sustainable development under the continuous improving construction of the system. The Asset Management Association of China (herein after referred to as "AMAC”)is authorized by the Funds Law, based on the industry self-discipline and supported by AM AC' s 7+2 self-discipline rule system, announced The Measures for the Administration of Private Investment Fund Service Business,specifying the business scope and responsibility requirements fbr the fund service organizations. Moreover, according to The Guidelines from the China Securities Regulatory Commission fbr the Valuation of Securities Investment Funds, in order to enhance the reasonability and reliability of the valuation, AMAC can establish fund valuation working mechanism. The action of AMAC to found the fund valuation team under the Custodian and Operating Committee (herein after referred to as "Committee” ) gradually establishes the valuation standards system fbr the industry.
The formation of the shadow price group in 2005 introduced the China Central Depository & Clearing Co., Ltd. (herein after referred to as"CCDC" ) as the first fund valuation benchmark organization, signaling the exploration of the asset management industry from market value method to fair value method. Since then, the money market funds have been using the valuation prices provided by CCDC as the shadow price to control the "deviation" indicator. Before, the valuation method used by the money market funds holds some similarity to the current financial products of banks, namely using the amortized cost method to adjust the return for the current period, in order to reach the purpose of controlling the level of the rate of return.The announcement of The Reference Method concerning the Valuation of Suspended Stocks in 2008 broke the traditional method of using market prices to value suspended stocks, recommended to use the method of fairer valuation and helped the fund industry cope with financial risks more effectively. The announcement of The Valuation Standards on Fixed Income Instrument in November, 2014 introduced China Securities Index Co., Ltd. as the second fund valuation benchmark organization, and formed the structure of multiple valuation benchmark organizations serving the fund industry. The announcement of The Guidelines for Valuation of Restricted Stocks in September, 2017 further clarified the range of restricted stocks, introduced the put options model for the first time, and focused on solving the valuation problem for the fair value of private placement investment funds. The No.90 Document on replacing business tax with value-added tax at the end of 2017 recognized the valuation benchmark organizations introduced by AMAC for the first time, which indicated that fair pricing should become the bond of the tax languages grafting in the asset management industry in the future. The announcement of The Guidelines for the Valuation of Unlisted Equity Investment in March, 2018 signaled that the exploration of fair value had extended to the area of unlisted equity investment, and greatly enhanced the value discovering capability of equity investment fund.The year of 2018 is the 20th anniversary of the founding of mutual funds, as well as the very first year for the big asset management industry. The New Regulation on Asset Management emphasizes that the fimdamental purpose of the asset management industry is to “serve the real economy” . Not only does the asset management industry need to be regulated, but also be developed. How to better fulfill the buyer' s pricing power of the asset management organizations is the very first proposition for all the organizations and employees in the asset management industry. Valuation ability is the core competitiveness of the asset management industiy. Asset management managers should focus on valuation during the whole fund life cycle including the fund raising, investment, management and redemption as well as strive to improve target valuation in order to discover and create value for investors. Improving the buy-side professional pricing ability will contribute to the game effectiveness in the capitahnarket. The valuation team will continue to respond and adjust to the demands from the industry development, and continuously improve China fund valuation standards system.
1.Continuous coverage of various investment targets
Currently, the valuation guidance system established by the valuation team has covered fixed income,equity and financial derivatives. There are six categories of eleven investment targets including "stocks, Shanghai-Hong Kong Stock Connect, restricted shares,pre-release of treasury bonds,fix income instrument,interbank deposit, stock price index futures, treasury bond futures,fund of fund, gold ETF, feeder fund and unlisted equity". In the next step, AMAC will dedicate to cover the valuation of all types of investment targets according to the development needs of the industry.The valuation standards system has been widely used in mutual funds,securities company asset management plans, special fund accounts,futures asset management, etc. and also expanded to the asset management industry including enterprise annuity,occupational annuity, insurance asset management, banks' wealth management, and trust plan. It is also applicable to proprietary investment businesses in the meantime. The valuation team will continue to explore and lead the use of fair value measurement tools, and promote the net value based management of asset management products.
2. Standardize the rules on accrual of performance fee
The essence o£ the fund is fiduciary finance service. Private fund managers provide professional entrusted wealth management services to qualified investors. Usually, they will charge two kinds of fees: one is the management fee based on the net asset value of the fund, and the other is performance fee calculated based on the fund performance or investors'asset appreciation.The purpose of collecting performance fee of private funds is to align the interests of managers with investors. A reasonable performance-based compensation mechanism helps to encourage managers to take appropriate risks and create higher returns for investors, which ultimately will achieve a win-win situation for managers and investors and the aim of return sharing.
The private fund industry has not yet formed unified accrual rules of performance fee. In practice, there exist problems such as complicated ways of collecting performance fee and inconsistent information disclosure. The valuation team is and will continue to guide private funds to establish standardized and reasonable performance compensation related mechanism, standardize business operations, clarify the contents of information disclosure, fairly treat investors and protect investors* interests.
3. Strengthen the research on taxation related policies in the asset management industry
As an important part of the national governance system, taxation holds the function of raising fiscal revenue, adjusting distribution,and promoting structural optimization. It plays an important role in servicing the reform and development of the new era and promoting social equality. In the asset management industry, the taxation arrangement promoting the equitable development of the industry is essential. The neutral tax burden and clear taxation mechanism are the basic requirements. The relevant taxation of asset management products should facilitate the circulation of financial capital and enhance the efficient allocation of financial capital into the real economy. As the bond between the fund language and the tax language, the valuation team continues to conduct the research on tax policy, facilitate the discussion in the industry, and build the foundation to accelerate the top-level design of the tax system in the asset management industry.
4. Standardize performance benchmark In modern finance, performance benchmark has become an important factor that can affect the market.For funds,an appropriate performance benchmark can accurately reflect the investment objectives and investment strategies of funds, so that investors can choose the appropriate funds according to their own risk—return preferences, and have relatively accurate analysis of manager * s investment capability. For fund managers, the performance benchmark determines the investment scope and investment objectives. If the management fee is linked to the performance benchmark, the performance benchmark will determine the final income from the management fee directly. For capital markets, if the scale of asset management with one index as the performance benchmark is large, then the fluctuation of the index will trigger a systematic change in the capital flow,further systemically affect the relevant assets. Since the performance benchmark has a significant impact on market participants and the market itself, plus the benchmark users have some deviation in practice,therefore the supervision on benchmark industry in the international markets becoming increasinglybetter. Currently, the valuation team is combining the international experience with the status quo of the Chinese market to formulate guidelines for fund performance benchmark,improve the phenomenon that domestic funds deviate from the benchmark,and further protect the interests of fund holders.
With the accelerating pace of the opening-up of China capital markets, the markets will attract more and more global participants after Shanghai-Hong Kong Stock Connect, Shenzhen-Hong Kong Stock Connect and the mutual recognition of funds. The rule is the right to speak. The standard is the stabilizer. The China fund valuation standards system will establish a dialogue platform for the international cooperation and communication of the fund industry and clarify business rules in the two-way opening of capital markets, which will definitely play an important role as the bridge and bond in the ubringing in” and “going out" of the fund industry.
In order to facilitate practitioners to learn and understand the fund valuation and improve the professional ability, AMAC has redacted the China Fund Valuation Guidebook 2018, which compiles the valuation standards published over the years and summarizes mature unlisted equity valuation practices.
Chairman of AMAC Hong LeiAug, 2018
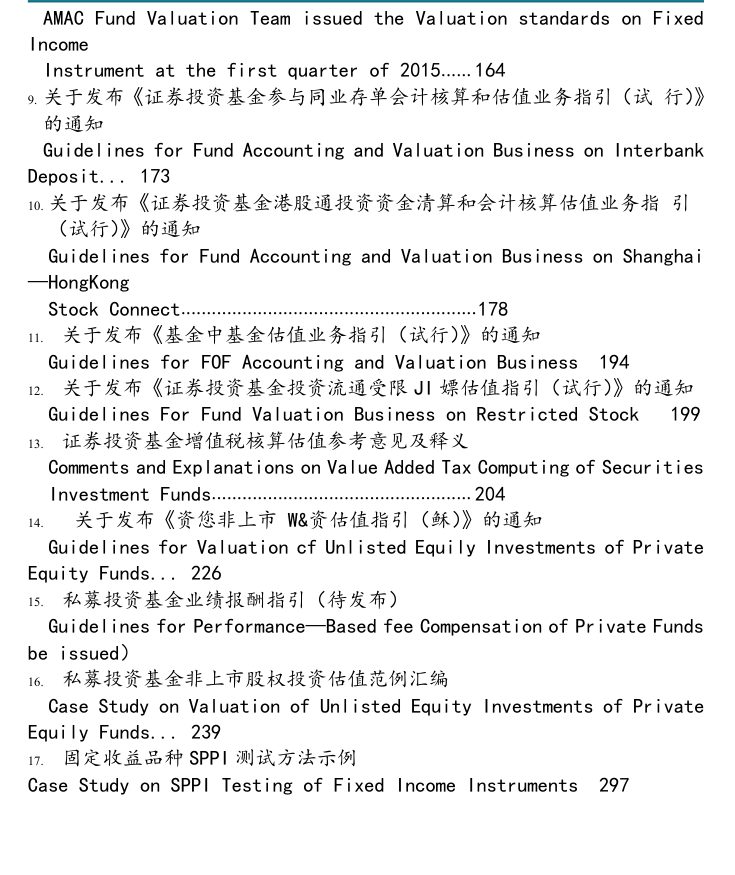
中国基金估值标准目录
CONTENTS
关于发布《中国证监会关于证券投资基金估值业务的指导意见》的通知1.Guidelines for Fund Valuation Issued by CSRC..... 1
关于发布《证券投资基金会计核算业务指引》的通知2.Guidelines for Accounting Business of Securities Investment Funds................................................................................................7
关于发布《证券投资基金股指期货投资会计核算业务细则(试行)》的通3.知Guidelines for Fund Accounting and Valuation Business on Stock Price Index Futures.... 68
关于发布中基协(AMAC)基金行业股票估值指数的通知4.Notice on Issuing AMAC Fund Industry Stock Valuation Index93 5. 关于发布《黄金交易型开放式证券投资基金及联接基金会计核算和估值业务指引(试行)》的通知Guidelines for Fund Accounting and Valuation Business on Gold ETFs.............................................................................................105 6. 关于发布《证券投资基金参与国债预发行交易会计核算和估值业务指引(试行)》的通知Guidelines for Fund Accounting and Valuation Business on Pre -issuance of Treasury Bonds............................................................. 126
关于发布资基金国醐货投资会计财业务细则(试行)》的通知7.8. Guidelines for Fund Accounting and Valuation Business on Ireasuiy Bond Futures ....141 关于发布《中国证券投资基金业协会估值核算工作小组关于2015 年]季度固定收益品种的估值处理标准》的通知AMAC Fund Valuation Team issued the Valuation standards on Fixed Income Instrument at the first quarter of 2015...... 164 9. 关于发布《证券投资基金参与同业存单会计核算和估值业务指引(试行)》的通知Guidelines for Fund Accounting and Valuation Business on Interbank Deposit... 173 10. 关于发布《证券投资基金港股通投资资金清算和会计核算估值业务指引(试行)》的通知Guidelines for Fund Accounting and Valuation Business on Shanghai—HongKong Stock Connect..........................................................178
关于发布《基金中基金估值业务指引(试行)》的通知11.Guidelines for FOF Accounting and Valuation Business 194
关于发布《证券投资基金投资流通受限JI 嫖估值指引(试行)》的通知12.Guidelines For Fund Valuation Business on Restricted Stock 199
证券投资基金增值税核算估值参考意见及释义13.Comments and Explanations on Value Added Tax Computing of Securities Investment Funds................................................... 204
关于发布《资您非上市W&资估值指引(稣)》的通知14.Guidelines for Valuation cf Unlisted Equily Investments of Private Equity Funds... 226
私募投资基金业绩报酬指引(待发布)
15.Guidelines for Performance—Based fee Compensation of Private Funds be issued)
私募投资基金非上市股权投资估值范例汇编16.Case Study on Valuation of Unlisted Equity Investments of Private Equily Funds... 239
固定收益品种SPPI 测试方法示例17.Case Study on SPPI Testing of Fixed Income Instruments 297